
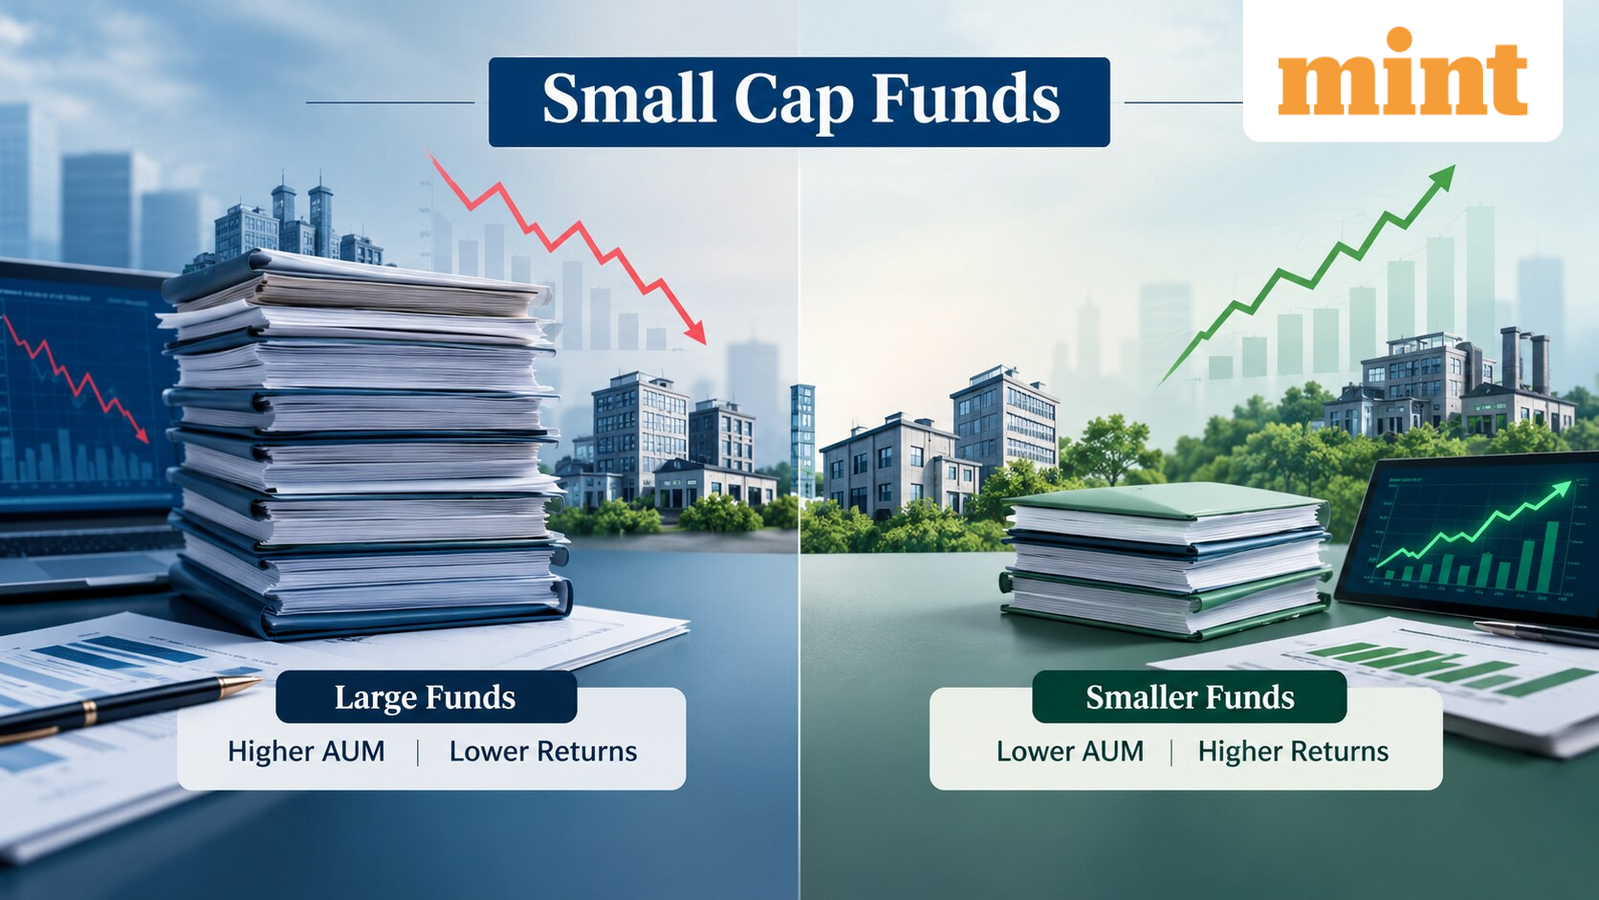
Investors generally look at big and popular mutual fund names and invest in them. However, small-cap funds with high AUM do not necessarily deliver better returns. AUM (Assets Under Management) is the total market value of the securities and cash managed by a mutual fund scheme on behalf of its investors.
According to Value Research data, Nippon India Small Cap Fund, the category’s largest scheme, with an AUM of ₹80,906 crore, delivered a 1-year return of -1.40% as of 23 October 2026. SBI Small Cap Fund, the second-largest, with an AUM of ₹41,059 crore, also posted a negative return of -2.33%.
In contrast, LIC MF Small Cap Fund, with an AUM of ₹841 crore, delivered a one-year return of 5.64%, while Bank of India Small Cap Fund, with an AUM of ₹3,671 crore, returned 16.71%, the highest in the category.
Here is what experts say about why smaller schemes can outperform larger peers and what investors should consider.
Why are high AUM small-cap funds delivering poor returns?
Vedant Gupte, Co-Founder and CEO of investment platform Trackk, said small-cap stocks often trade in low volumes, making it difficult for big funds to build or exit positions without affecting prices.
“A very big fund cannot put enough money into its best small ideas, so it spreads across many more stocks, drifts towards larger and more liquid companies, and often holds more cash. Each of these choices dilutes its returns,” he added.
Ajay Kumar Yadav, CFPCM, Group CEO & CIO, Wise Finserv explained this through an example. Suppose the fund managers of Nippon India Small Cap Fund and LIC MF Small Cap Fund identify the same promising company. Both want to invest 2% of their respective portfolios in that stock.
For LIC, which manages approximately ₹841 crore, a 2% allocation would mean investing about ₹16.82 crore. For Nippon, managing around ₹80,906 crore, the same allocation would require approximately ₹1,618 crore. Now imagine that the company has shares worth ₹20 crore being traded on an average day.
If the managers decide not to account for more than 10% of that day’s trading value, LIC could theoretically complete its purchase in about 9 trading sessions. Nippon, on the other hand, would need more than 800 trading sessions under those same assumptions.
“For a very big fund, buying substantial quantities of a relatively illiquid stock may push up its share price. That increases the average purchase cost and can reduce the return potential,” he added.
Eshaan Lazarus, Founder and CEO of 021 Trade, cited a March 2026 IIM Kozhikode paper that found a stronger negative relationship between fund size and risk-adjusted returns in the small-cap segment. As illiquid investment opportunities become constrained, larger funds may be pushed towards more liquid, lower-alpha stocks.
Does the relationship between AUM and returns change over longer periods?
Yadav said it can. Nippon India Small Cap Fund delivered annualised returns of 17.04% over five years, compared with 15.65% for LIC MF Small Cap Fund. Over seven years, Nippon returned 25.24% annually, while LIC delivered 21.45%.
Gupte said the advantage of being small tends to fade over time, mainly because it destroys itself. When a small fund performs well, it attracts money (inflows), grows large, and then faces the same liquidity problems that its bigger peers do.
Lazarus added that this is consistent with Berk and Green’s 2004 theoretical model, which explains how inflows can consume a skilled fund manager’s investment opportunities. A manager’s skill may remain unchanged, but a larger pool of money can make it harder to sustain the same level of outperformance.
How should investors analyse small-cap funds?
Yadav suggested a broad screening approach, assigning around 75% importance to long-term return consistency, and 25% to AUM-related factors such as fund capacity and portfolio liquidity. He recommended the following checks:
- Look at three-year and five-year returns, extending to seven years. Calendar-year and rolling returns can help establish whether performance has been consistent or concentrated in favourable periods.
- Examine AUM in relation to the portfolio. Look at the number of holdings, average market capitalisation, concentration in the largest stocks and liquidity characteristics.
- Examine standard deviation, downside risk, drawdowns and risk-adjusted measures such as the Sharpe ratio.
Lazarus recommended checking the expense ratio and fund manager’s tenure. Compare direct plans with direct plans and regular plans with regular plans, and assess how much of a scheme’s three-, five- or 10-year performance history was generated under its current manager.
Gupte said the monthly stress test that every small-cap fund now publishes is the most useful tool here, because it shows how many days the fund would need to sell a large part of its portfolio. Fewer days means better liquidity.
“Fund size matters most in small-cap funds, somewhat in mid-cap funds, and very little in large-cap funds, where markets are deep enough to absorb big trades,” he added.
Disclaimer: This story is for educational purposes only. The views and recommendations made above are those of individual analysts or broking companies, and not of Mint. We advise investors to check with certified experts before making any investment decisions.
About the Author
Sheetal Goel is a Content Producer at Livemint, where she covers corporate developments, personal finance, business trends, markets, and SEBI-related updates. She focuses on simplifying complex financial concepts and presenting them in a clear, reader-friendly manner, thereby helping audiences better understand investment trends, personal finance, and market developments. Her writing focuses on making finance more accessible to everyday readers while maintaining clarity, accuracy, and relevance. <br><br> She holds a degree in Economics (Hons.) along with an MBA in Finance, which has helped her develop a strong foundation in financial analysis, market understanding, and business reporting. Before joining journalism, she worked with finance and broking firms, where she closely followed market developments, investment strategies, and evolving industry trends. This practical exposure strengthened her understanding of financial markets. She has also written content across multiple formats and platforms, including YouTube, LinkedIn, and Instagram. <br><br> Over time, she has developed expertise in covering market-linked stories, investor-focused topics, and regulatory updates in a simplified yet informative style. She also enjoys reading and listening to Hindi poetry, reflecting her appreciation for literature and creative expression beyond the world of markets and numbers.